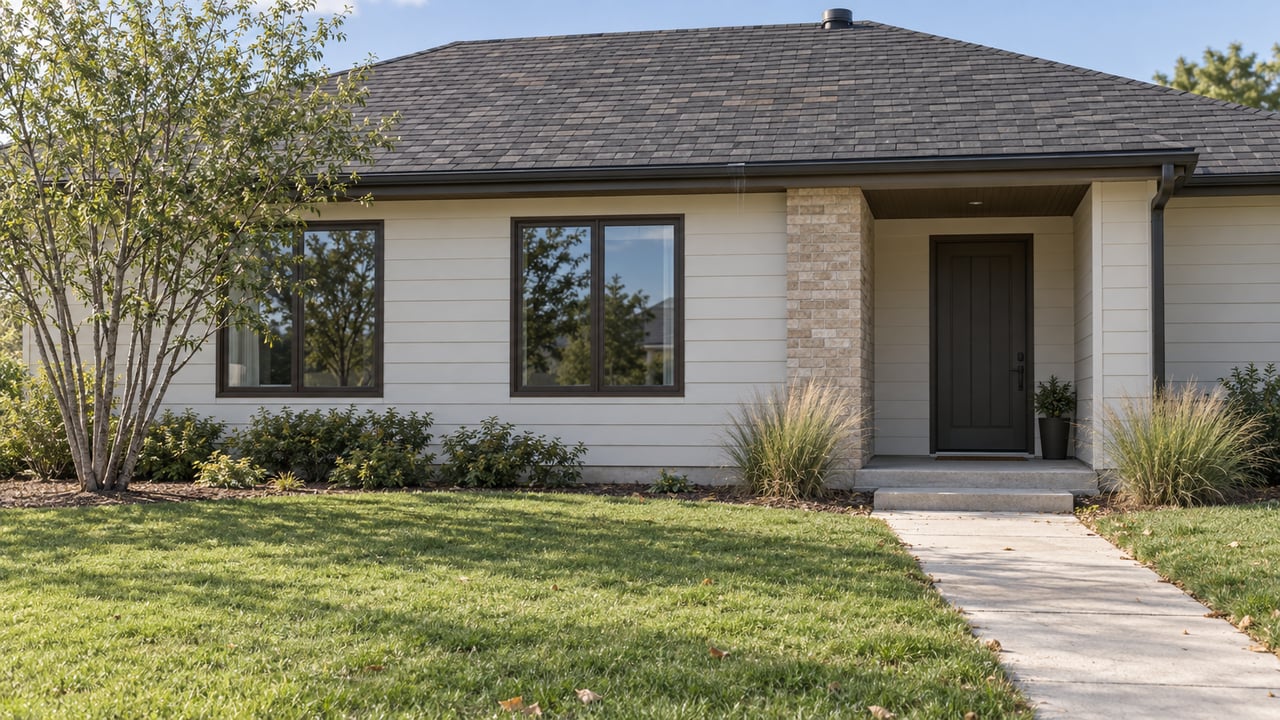
In Aurora, the Roof Doesn't Just Need to Pass Inspection. It Needs to Pass Underwriting.
October 1, 2026
October 1, 2026
A buyer makes an offer on a house in Aurora. The seller accepts. The inspector walks the roof, notes wear that's normal for its age, and clears it without flagging anything. Then the buyer calls to bind homeowners insurance and the quote comes back high enough to change the monthly payment by a few hundred dollars, or a carrier declines to write the policy until the roof is replaced. Nobody did anything wrong. The roof passed inspection. It didn't pass underwriting.
That gap between what an inspector checks and what an insurer prices is becoming the real friction point in Aurora real estate, and it's worth understanding before you write an offer or sign a listing agreement, not after.
For years, agents in this part of the state have said hail drives insurance costs. In February 2026, the Colorado Division of Insurance put an actual figure on it: hail accounts for somewhere between 26 and 54 percent of a homeowner's premium, depending on the county, and that share runs closer to 50 percent along the Front Range and the Eastern Plains, where Aurora sits.
One comparison site's Colorado analysis from May 2026 put Aurora's average annual homeowners premium at $4,323, clustered right alongside Denver and Colorado Springs near the state average. Fort Collins and Loveland, farther north where hail frequency tapers off, ran 12 to 13 percent below that same average. The gap isn't about home values or square footage. It's geography.
Aurora hasn't just been in the path of Colorado's hail problem. It's been at the center of it. The May 8, 2017 storm remains the most expensive insured catastrophe in state history at roughly $2.3 billion, and it hit Aurora directly with baseball-sized hail. The May 30, 2024 storm caused another $1.9 billion in damage statewide, and Aurora took a direct hit again.
Local roofing contractors who track Doppler radar data report more than 195 hail detections at or near Aurora over the past decade, with 115 ground-level spotter reports filed in the past year alone. The 80017 zip code shows some of the highest damaging-hail counts in the metro. One independent hail-tracking service, drawing on a decade of NOAA radar data, scores Aurora 90 out of 100 for hail frequency. Aurora stretches across three counties and catches storms rolling off both the Palmer Divide and the eastern plains, which is part of why its eastern neighborhoods see some of the heaviest hail in the region.
The city's own building code reflects this. Aurora Roofing Co. reports that Aurora requires ice-and-water barrier underlayment on every roof built in the city. Parker doesn't require it at all. Douglas County only requires it above 7,000 feet in elevation. Aurora treats hail and ice as a baseline construction risk, not an occasional weather event.
Buyers comparing an older bungalow to a 2000s-era build in Aurora often assume the newer house will be cheaper to insure. The data says otherwise. Colorado's insurance pricing shows middle-aged homes, roughly 20 to 25 years old, costing more to insure than older homes, because a home built around 2000 typically still has its original roof sitting right in the window where hail damage peaks. Meanwhile, older homeowners have often already replaced theirs at some point over the decades. A well-maintained 1970s home with a five-year-old roof can undercut a 2000-era home still on its original shingles.
What this means in practice: when you're evaluating a house in Aurora, the year the roof was last replaced tells you more about your future premium than the year the house was built. It's a question worth asking the seller directly, and one worth confirming with documentation rather than taking on faith.
Class 4 impact-resistant shingles are the material most Colorado insurers reward, with discounts typically ranging from 15 to 35 percent off the wind and hail portion of a premium. But that discount is not automatic. Carriers don't scan county permit records or monitor roof replacements on their own. A homeowner has to supply three things: qualifying Class 4 materials on the roof, a closed building permit for the work, and the manufacturer's certification submitted directly to the carrier.
Permit fees and inspection timelines aren't uniform across the metro either. Denver, Aurora, and Lakewood each run their own schedules, which matters if you're timing a re-roof around a sale or a purchase and don't want a permit sitting open when you need documentation in hand.
There's a legal shift coming that will change how enforceable this discount is. Governor Polis signed SB26-155 on June 8, 2026, creating the Strengthen Colorado Homes Enterprise inside the state's Division of Insurance. Starting no sooner than January 2027, insurers will have to prove in their rate filings that savings from resilient roofing actually reach policyholders, which makes the discount an enforceable requirement rather than a voluntary offer. That enforcement mechanism isn't live yet. Right now, whether you get the full discount still depends on your specific carrier and whether the paperwork was filed correctly.
Here's how that plays out on four common roof situations in Aurora right now:
| Roof documentation | What underwriting typically sees |
|---|---|
| Original shingles, home built around 2000 | Roof at or near 20-25 years old, standard pricing, no discount available |
| Storm-damaged, repaired without a closed permit | No documentation trail, priced as if original or unverified |
| Class 4 shingles installed, permit and certification not yet filed | Materials qualify, discount not automatically applied |
| Class 4 shingles, permit closed, certification filed with carrier | Full discount eligibility, typically 15 to 35 percent off wind/hail premium |
The material difference between the bottom two rows is entirely paperwork. That's an easy thing to fix and an easy thing to miss.
According to CountryW, Colorado law generally gives homeowners about a year from a storm date to file a hail claim, though the exact window depends on the policy. If a storm hit your roof and you never filed, or filed and settled for an actual cash value payout rather than a full replacement cost payout, it's worth understanding the difference before you list. An ACV settlement pays the depreciated value of the damaged roof, which can be significantly less than what it costs to replace it today. A roof that was "repaired" under an ACV claim may still be older material closer to the end of its usable life than a casual look would suggest.
Sellers who have had roof work done since a storm should pull together the permit closure and manufacturer certification before listing, not after an offer comes in. It gives buyers, appraisers, and their insurance carriers a documented answer instead of a guess, and it prevents the deal from stalling while someone tracks down paperwork during an active contract.
Hail pricing doesn't stop at single-family homes. Aurora HOA insurance in 2026 typically runs $20,000 to $85,000 a year for smaller townhome-style associations, and $50,000 to $180,000 for mid-sized condo or townhome communities with shared roofs and exterior coverage. Larger associations with multiple buildings, pools, or garages can exceed $200,000 to $450,000 annually. Hail is a major driver of those numbers, and many Colorado associations have raised their wind and hail deductibles in response to repeated storm losses.
Anyone buying a condo or townhome in Aurora should ask for the HOA's insurance declarations page and deductible structure before waiving any contingencies, and should talk to their own agent about loss assessment coverage layered on top of the HOA's policy.
Does a newer home in Aurora always mean a lower insurance quote? No. Roof age and material class carry more weight with underwriters than the year the house was built. A 25-year-old original roof on a 2000s build can price higher than a much older home with a recently replaced roof.
What should sellers do before listing if the roof took hail damage in the past year? Confirm whether a claim was filed and settled, and if repair work was done, make sure the permit is closed and the manufacturer's certification is on file. That documentation answers the buyer's insurance question before it becomes a delay.
Does this apply the same way to condos as it does to single-family homes? Partially. The HOA's master policy absorbs much of the building's hail exposure, but individual owners still need their own coverage, and loss assessment protection matters more in a market where HOA deductibles are rising.
None of this is a reason to think twice about Aurora. It's a reason to make one phone call before you write an offer instead of after you're already under contract. Live.Laugh.Denver. walks Aurora buyers and sellers through the roof and insurance conversation early, so the underwriting call never becomes the closing-day surprise.
This article is general information, not legal, tax or financial advice. Consult a qualified professional about your situation.
Stay Up To Date on The Latest Real Estate Trends
There's a number that measures how happy your house makes you. In a month built around gratitude, it might be a great number worth looking at.
Elevate your real estate career with Live.Laugh. Join our supportive, community-driven team and access expert guidance, innovative marketing, and a culture of growth. Let’s build something amazing together!
Sign up for our newsletter to receive exclusive updates, expert tips, and the latest real estate insights directly to your inbox!
(720) 663-0022
[email protected]
2405 E 28th Avenue
Denver, CO 80205